Fourteen Years of Distress Prediction Research
Our team began with a single observation: most bankruptcy models treated every industry as
identical. That assumption produced noisy signals and costly false negatives. We built our
framework differently.
Explore methodology
Build the Dataset
We assembled financial statement histories across sectors and market cycles, standardizing definitions so that a retail ratio and a utility ratio speak the same language.
0%
Researchers and Practitioners Behind the Framework
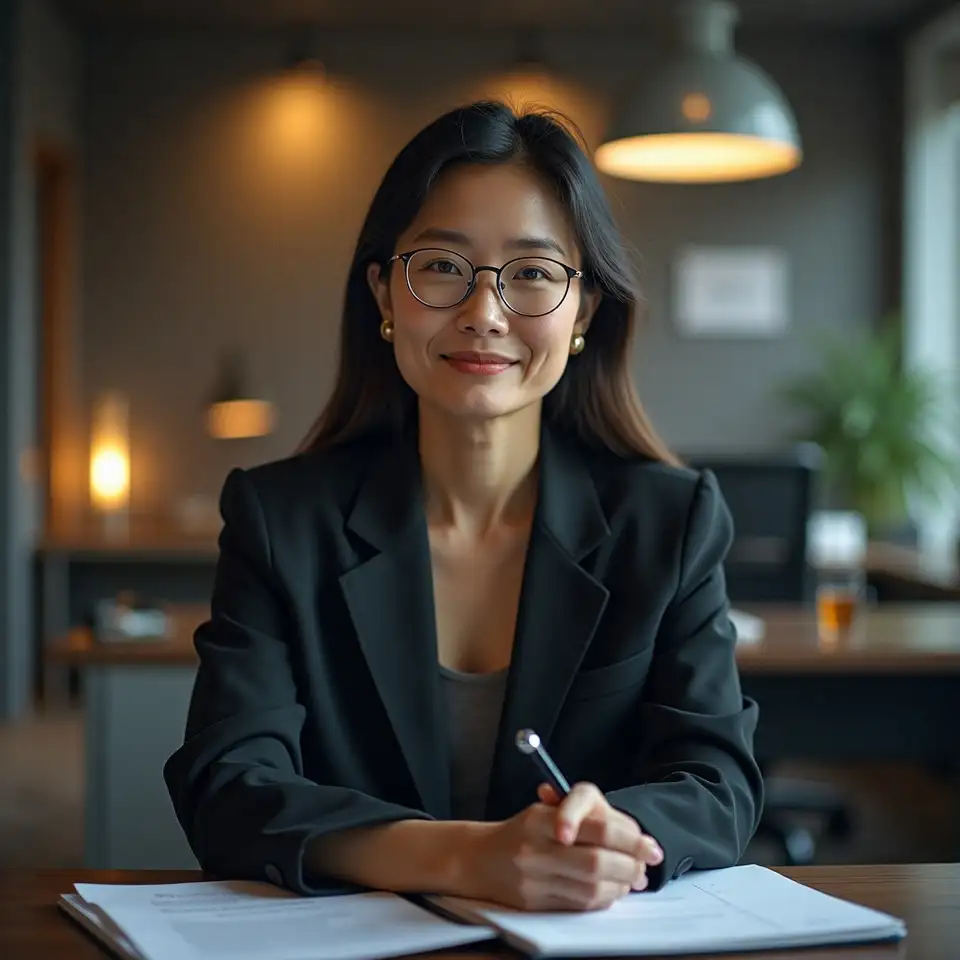
Dr. Eleanor Whitmore-Chen
Founding Research Director
Eleanor spent twelve years in academic econometrics before translating her bankruptcy forecasting research into practitioner-facing tools. She leads model architecture and validation protocol design.
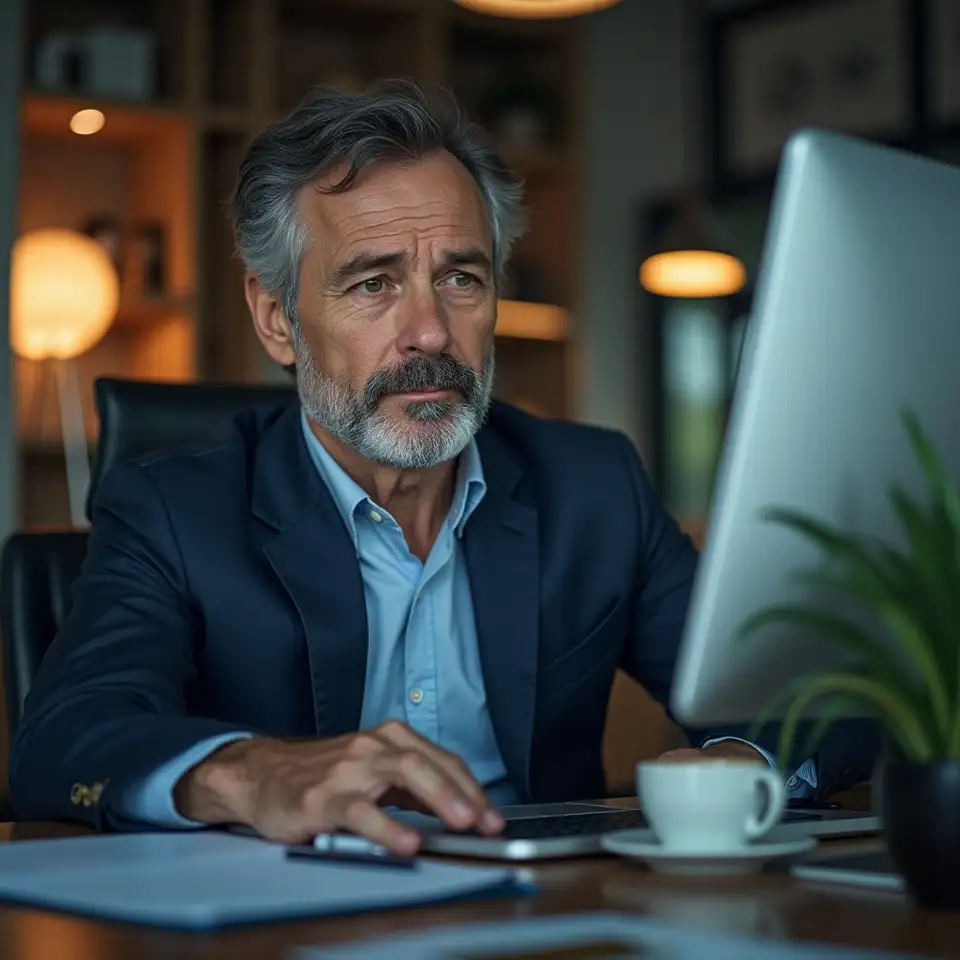
James R. Holloway
Lead Quantitative Analyst
James builds the statistical pipelines that transform raw filings into standardized features. His background spans credit risk modeling and computational statistics across three continents.
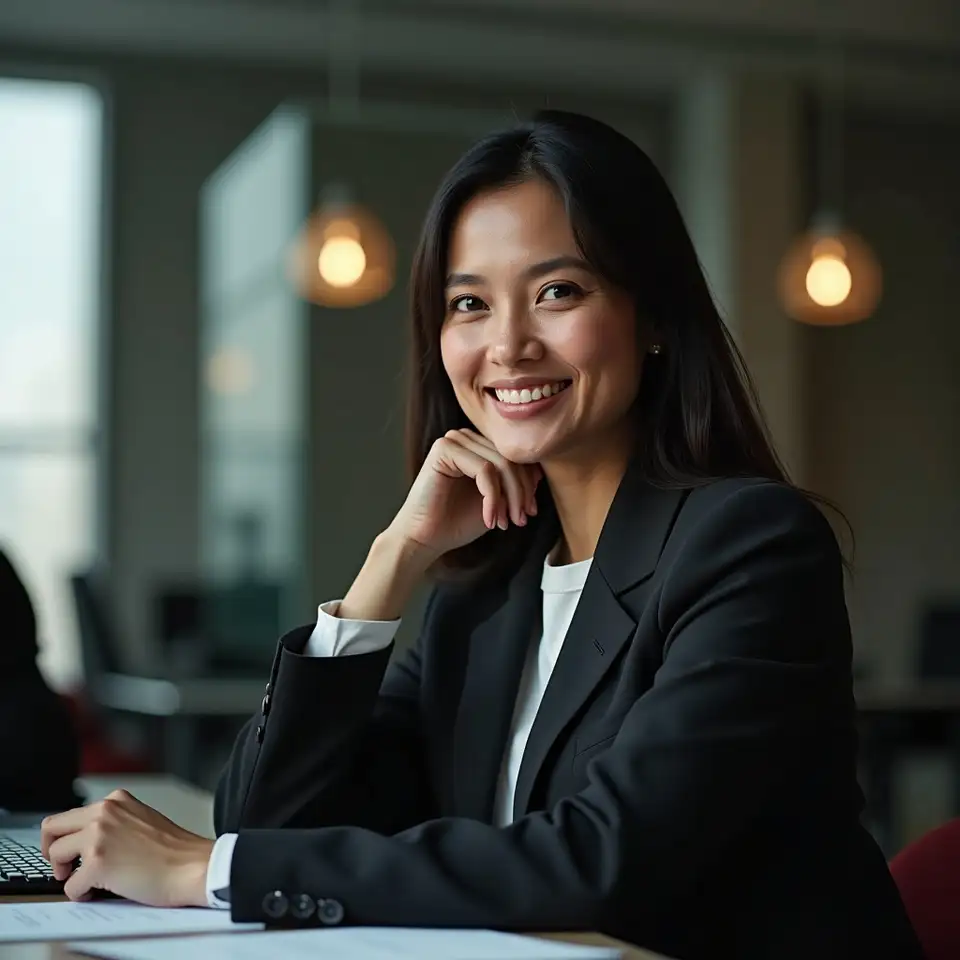
Priya Natarajan-Bell
Sector Calibration Specialist
Priya ensures that each industry model respects the capital structure realities of its sector. She previously developed rating methodologies for two major agencies.
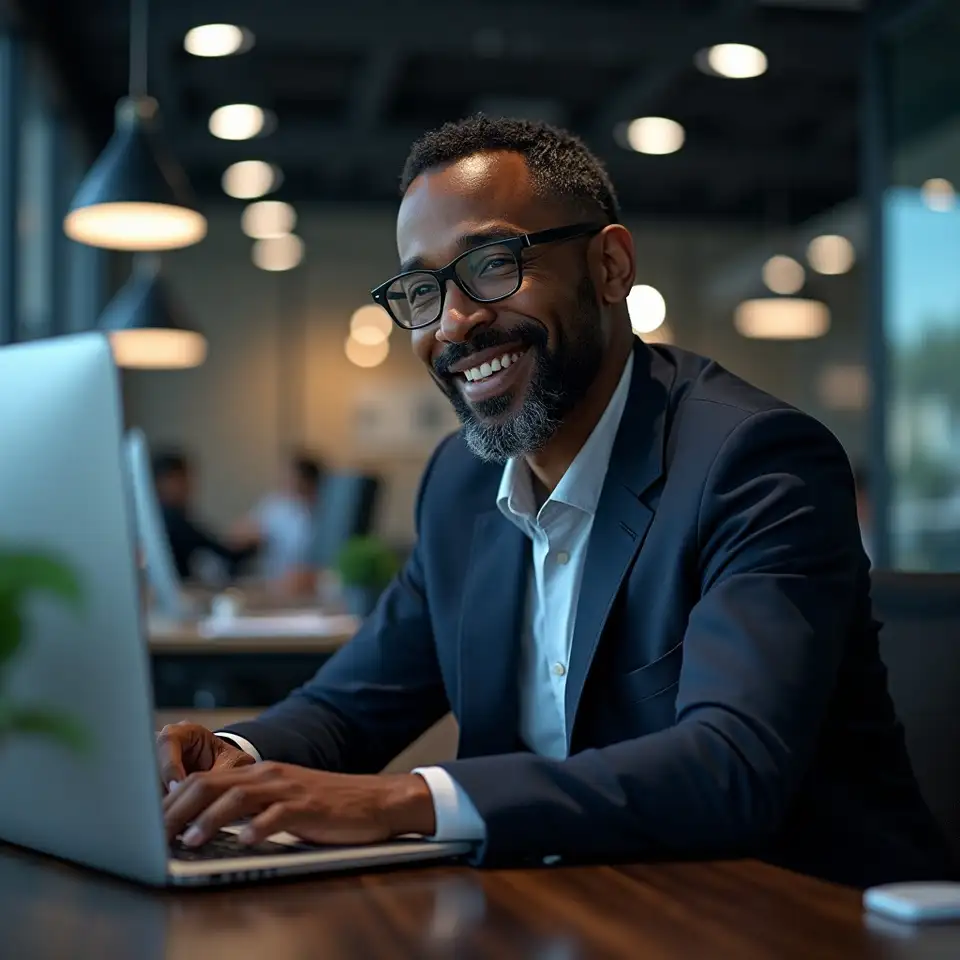
Dr. Marcus Oduya
Machine Learning Research Lead
Marcus bridges traditional econometrics and modern predictive methods. His work focuses on maintaining interpretability while capturing nonlinear distress signals.
Sarah Lin-Okonkwo
Data Integrity Director
Sarah governs the ingestion, cleaning, and lineage of every dataset we use. She established the protocols that keep our historical comparisons consistent across decades.
Henrik Voss-Johansen
Practitioner Liaison
Henrik translates model outputs into decision frameworks for institutional users. He ensures that academic rigor does not become practitioner opacity.
Our Path
2012
Initial Research
Eleanor Whitmore-Chen published the first paper demonstrating that sector-specific calibration materially improved bankruptcy prediction accuracy compared to one-size-fits-all approaches.
001
2016
First Partnership
A regional credit fund adopted our early framework for its internal screening process. Their feedback reshaped how we presented uncertainty intervals and model confidence scores.
002
2019
Platform Launch
We released the first version of our current platform, combining traditional Altman-style ratios with machine learning classifiers trained on post-crisis data.
003
2023
Cycle Validation
Following the 2022 market correction, we completed a full retrospective validation. Three models were retired, two were recalibrated, and one new architecture entered testing.
004
2026
Current Framework
Today's platform integrates fourteen years of research, practitioner feedback, and methodological refinement. We continue to publish findings and welcome critical peer review.
005
Recognition
2024
Research Transparency Award
Honored for publishing full methodological limitations alongside predictive results, setting a standard for honest reporting in quantitative finance research.
Best Predictive Paper
2019
Open Data Initiative
2021
2023
Methodology Innovation
2025
What Guides Our Work
Our values are not decorative statements. They shape which projects we pursue, which
partnerships we accept, and how we respond when our models underperform.
Test Everything
Every claim we make about model performance must be reproducible. We maintain versioned datasets and documented code so that independent researchers can verify our results.
Document Assumptions
All models rest on assumptions about stationarity, distribution shape, and variable relevance. We make these explicit so users understand where the ground may shift.
Publish Limitations
Open Methodology
Useful Outputs
Feedback Loops
Fair Application
Predictive tools can amplify existing biases. We audit our models for disparate impact across firm size, geography, and ownership structure before deployment.
No Misuse
Scheduled Review
Incorporate Critique
Explain Clearly
Complex methods need plain exposition. We invest in writing and visualization that make our approaches accessible to non-specialist decision makers.
Build Literacy
We contribute to public understanding of distress prediction so that users can evaluate any model, including our competitors, with informed skepticism.